HDB Renovation Guide Singapore: Personal Loan vs Reno Loan
Paying for a reno is a separate decision from designing it. This HDB Renovation Guide Singapore compares the renovation loan against a personal loan, how milestone payments work, and how to line cash up with the works. Read before you borrow for 2026.
Reno loan basics
A renovation loan runs up to S$30,000, or six times your monthly income, whichever is lower. Rates sit around 3.5% to 4.5%.
The term maxes at 5 years. Banks disburse it in stages tied to your renovation progress, not as one lump.
This keeps the debt matched to the work. You do not sit on cash you have not earned yet.
Personal loan vs reno loan
A personal loan is more flexible but often costs more and pays out in full at once. You hold the balance from day one.
The reno loan caps at S$30,000, so bigger 5-room resale jobs may need topping up from savings or a second facility.
Rates on personal loans vary, but the staged release of a reno loan is the real advantage for cashflow.
- Reno loan: capped, staged, lower rate, tied to works.
- Personal loan: flexible, lump sum, pricier, yours to spend.
- Both need repayment within the term you pick.
Milestone payments protect you
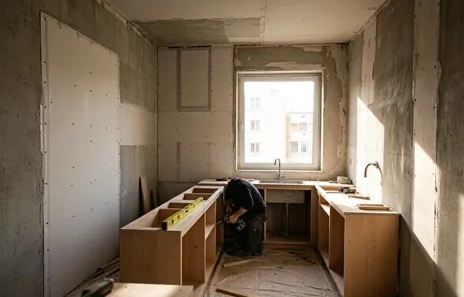
Good quotes use milestone payments: deposit, progress payments, and a retention sum held until defects clear.
The retention sum is your leverage. The contractor fixes the 1-year warranty items before you release the last cheque.
BTO flats carry a 1-year defect liability with the builder, separate from your contractor's warranty. Track both.
HDB Renovation Guide Singapore: align cash with works
Match each loan disbursement to a payment milestone. Deposit on sign, progress on carpentry and tiling, retention at end.
A 4-room BTO runs about 8-12 weeks. Resale runs 12-16 weeks. Your drawdown schedule should follow that clock.
Keep 10-15% contingency outside the loan if you can. Borrowing the buffer costs interest you may not need to pay.
Your HDB BTO renovation budget should map to these milestones, and a HDB-approved contractor keeps permit works clean so progress stays on track.
When a personal loan makes sense
If your reno stays under the cap and you want staged control, the reno loan wins. But a personal loan fits a specific case.
Use it when the job exceeds S$30,000 and you already hold the cash for part of it. Borrow the gap, not the whole build.
The lump sum also helps if you must pay a supplier upfront for quartz or custom carpentry before the reno loan can disburse.
- Reno loan: best for standard flats within the cap.
- Personal loan: best for topping up a large resale job.
- Either way, keep the retention sum outside the borrowed amount.
I size the loan to the works, then hold savings for the buffer. Borrowing the contingency doubles its cost through interest.
The right loan is the smaller one that fits the works. Stage it to the milestones and the money follows the hammer, not the other way round.